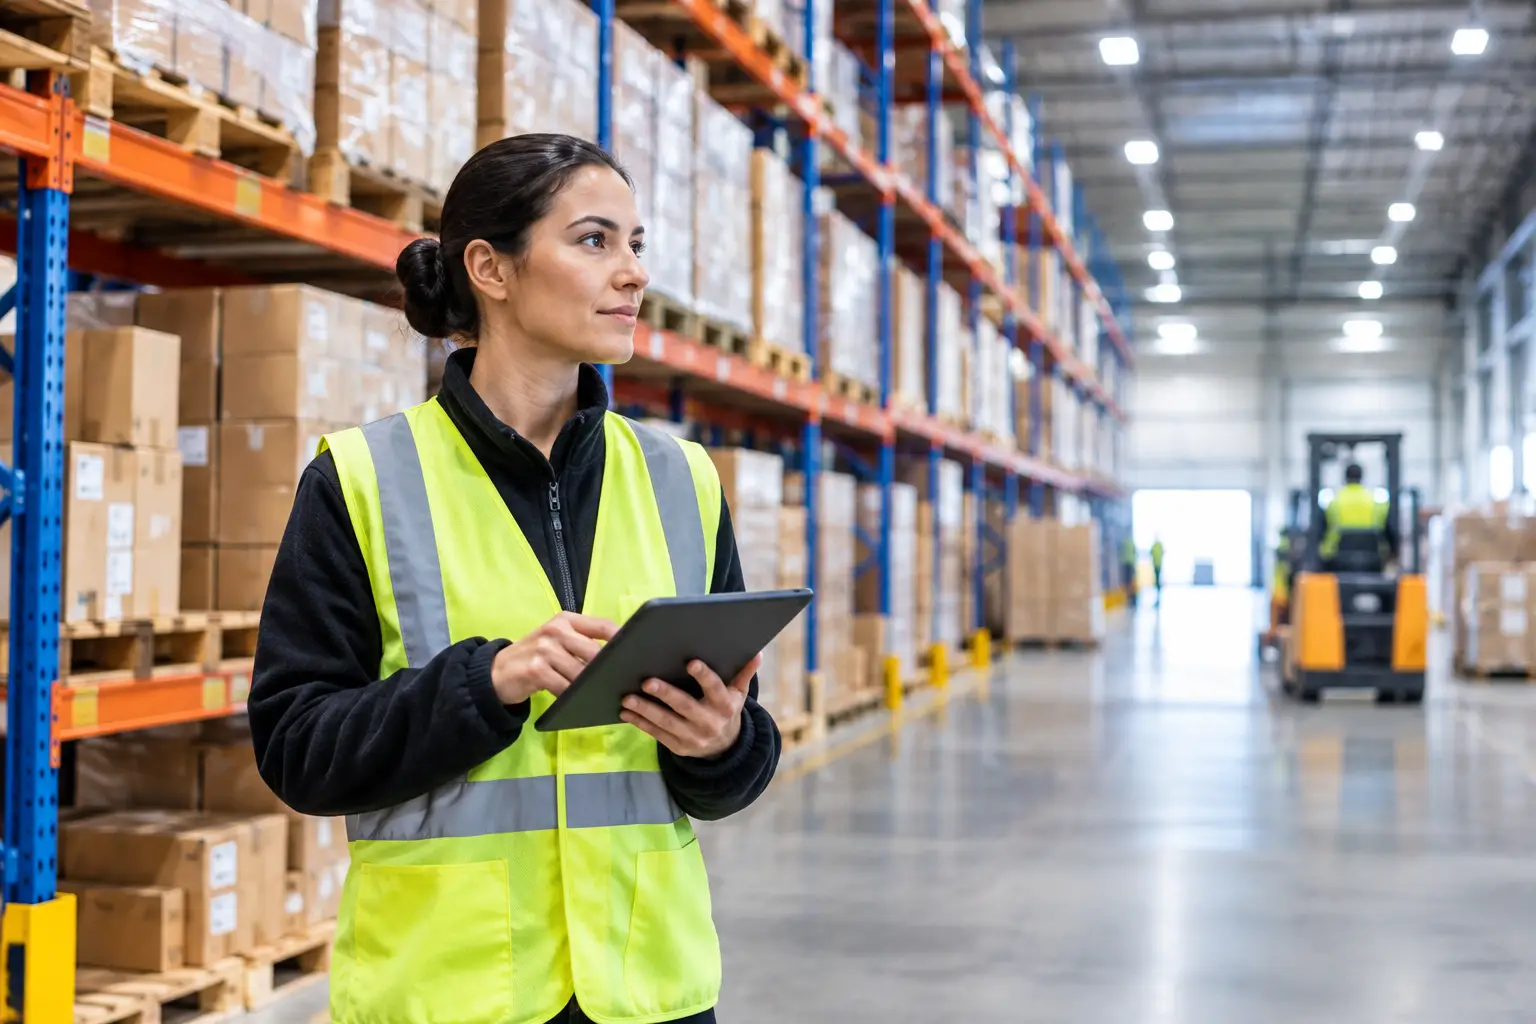
3PL Warehousing Market Trends Shaping GTA Space
By Michael Law · Industrial Real Estate Broker, Lennard Commercial Realty
A 3PL operator can outgrow a warehouse long before its lease expires. A new customer contract, a shift from pallet storage to fulfillment, or a need for later shipping cutoffs can change the real estate requirement quickly. That is why 3PL warehousing market trends matter to industrial owners, investors, and occupiers across the Greater Toronto Area.
Third-party logistics providers sit between retailers, manufacturers, importers, and end customers. Their facilities must absorb changing volumes while meeting service commitments that are often measured in hours, not days. The result is continued demand for functional industrial space, but the definition of a suitable building has become more specific.
3PL Warehousing Market Trends Driving Decisions
The broad industrial market may be discussed in terms of vacancy, rents, and new supply. For 3PL users, those measures only tell part of the story. A warehouse can be available and still be operationally unsuitable due to poor truck access, limited loading capacity, low clear height, weak power, or a location that adds time to every delivery route.
The most significant current trend is the move toward selective demand. 3PLs still need space, but they are more deliberate about where and how they commit. After a period when growth often required taking any available warehouse, operators are assessing labor access, transportation cost, building efficiency, and customer concentration with greater discipline.
For landlords, this means a well-located, functional building can remain highly competitive even when market conditions give tenants more choice. For tenants, it creates an opportunity to improve operations rather than simply renew a lease because moving is disruptive.
Location remains a service-level decision
GTA logistics operations are shaped by congestion, highway access, customer density, and the cost of getting a truck to its next stop. Facilities in Mississauga, Brampton, Vaughan, and other established distribution nodes remain attractive because of their connection to major transportation routes and the concentration of labor and customers.
However, proximity comes at a cost. Higher occupancy costs in core locations may be justified for fulfillment-intensive operations with frequent deliveries and tight service windows. For bulk storage, slower-moving inventory, or regional consolidation, a less central location may provide a better overall cost structure.
The right answer depends on the freight profile. A 3PL serving local retail replenishment has different priorities from one handling containerized imports, food distribution, building materials, or business-to-business orders. Real estate decisions should follow the operating model, not a generalized map of where industrial space is available.
Building functionality is being priced separately
Warehouse square footage is no longer a useful stand-alone comparison. Clear height, trailer parking, dock door ratio, shipping court depth, bay size, sprinkler capacity, power, and circulation all affect how much revenue a 3PL can generate from a facility.
Modern distribution buildings can support denser storage, more efficient order flow, and better trailer management. Yet newer is not automatically better. Older industrial properties can be highly effective when they offer the right loading configuration, sufficient yard area, and a location close to customers. A lower rent can lose its appeal quickly if inefficient loading creates labor costs, missed appointments, or carrier delays.
Owners considering capital improvements should focus on the features that solve actual tenant constraints. Adding dock equipment, improving site circulation, upgrading lighting, or creating trailer parking may carry more leasing value than cosmetic work. The most useful upgrade is the one that makes a building easier to operate every day.
E-commerce has matured, but fulfillment pressure remains
E-commerce growth has become less explosive than its peak-period pace, but consumer expectations have not returned to slower delivery standards. Retailers continue to use 3PL partners to manage variable order volumes, returns, inventory placement, and peak-season capacity.
This supports demand for facilities that can handle pick-and-pack operations, parcel shipping, and reverse logistics. These uses often require more labor, technology, and operational layout than traditional pallet-in, pallet-out warehousing. They may also place greater emphasis on parking, employee access, office area, and reliable utilities.
Not every 3PL needs a dedicated fulfillment building. A blended operation may need both high-throughput fulfillment space near customers and more economical overflow or reserve storage elsewhere. Splitting functions across two properties can add handling costs, but it can also lower occupancy costs and reduce pressure on a primary facility. The decision should be tested against actual order and transportation data.
Labor, automation, and power are changing site requirements
Warehouse labor remains a material operating consideration. In a tight labor submarket, a building with difficult employee access or limited nearby amenities can make recruiting and retention harder. Transit access, parking availability, and commute patterns matter more for labor-intensive fulfillment operations than for lightly staffed storage facilities.
Automation is also influencing leasing decisions, although its impact varies. Conveyance systems, sortation, automated storage, and warehouse management technology can increase throughput and reduce dependence on manual processes. They can also create requirements for power, floor conditions, clear height, fire protection, and long-term lease certainty.
For an owner, a tenant investing heavily in automation may be a stable long-term occupier. For the tenant, specialized improvements create a risk: the building may become difficult or expensive to replace if the operation expands or changes. Lease terms should address improvement ownership, restoration obligations, power capacity, expansion rights, and renewal options before capital is committed.
More supply does not mean every tenant has leverage
New construction and returning space can improve choice in some industrial submarkets. That can moderate rent growth and give qualified tenants more negotiating room than they had during exceptionally tight conditions. It does not mean that every 3PL can expect discounted, move-in-ready space.
High-quality facilities with strong loading, trailer parking, and highway access remain limited. Large contiguous blocks are not interchangeable with smaller bay industrial properties, and specialized users may have a narrow set of viable options. A tenant seeking significant racking capacity, outdoor storage, temperature control, or heavy shipping volumes will often face a more constrained search than headline vacancy figures suggest.
This is where timing matters. A 3PL evaluating a relocation should begin well before its lease deadline, particularly if it has specialized requirements. The process includes defining the operational specification, reviewing potential sites, assessing fit-out time, negotiating business terms, and planning the move without disrupting customer service. Waiting for the final months of a lease usually narrows options and weakens negotiating leverage.
What owners and investors should watch
For industrial owners, the central question is not simply whether a property can lease to a 3PL. It is whether the property can support a 3PL's operating model better than competing buildings. A facility with strong access, adequate loading, usable yard space, and adaptable interior configuration can appeal to a wider pool of logistics users.
Investors should also distinguish between demand that is contractual and demand that is speculative. A 3PL with diversified customers, durable client relationships, and a disciplined real estate footprint presents a different credit and renewal profile from an operator dependent on one fast-growing account. Reviewing the tenant's business model, customer concentration, lease structure, and capital needs provides a clearer view of risk than the 3PL label alone.
For tenants, the current market favors careful comparison rather than assumptions. Base rent is only one part of occupancy cost. Property taxes, operating expenses, utilities, labor travel, freight miles, material handling limits, and the cost of a poorly planned move can outweigh an apparent rent saving.
The practical opportunity is to treat the warehouse as a service asset, not just a real estate expense. When the building, location, and lease structure match the logistics strategy, the property can support better service and more durable margins. That is the standard worth applying before the next expansion, renewal, or acquisition decision.
About Michael Law
Managing Partner and Industrial Real Estate Broker at Lennard Commercial Realty. Representing tenants and landlords across Toronto and the GTA for 15+ years. Michael specializes in GTA industrial real estate — connect with Toronto's leading industrial broker at mlawrealestate.com/industrial-broker-toronto.
Related Articles


More Toronto Industrial Real Estate Insights
Articles & Analysis
Toronto 3PL Warehouse Site Selection Guide
Read →GTA Truck Access: Check the 5 km LCV Rule Before Leasing
Before signing a GTA industrial lease, verify the 5 km LCV access rule, Toronto delivery exemptions, turning clearance, and 407/401 corridor economics.
Read →Food Grade Warehouse Leases in Ontario: 2026 Rents, Rules and Risks
Compare 2026 GTA rents and availability, verify federal and Ontario food safety rules, and get broker support for lease checks before signing.
Read →GTA Industrial Outlook for Owners and Occupiers
Read →GTA Warehouse Availability 2026: 2.7% Vacancy, Tenants Act Fast
GTA warehouse availability sits near 4.4%, while vacancy is 2.7%. See how rents, sublease supply, and tenant tactics shape a 2026 search.
Read →Common Questions
What is a sale-leaseback in industrial real estate?
A sale-leaseback is a transaction in which an industrial property owner sells their building to an investor and simultaneously signs a long-term lease to remain in the property as a tenant. The seller unlocks the capital tied up in their real estate while retaining full operational use of the facility. The buyer acquires a tenanted investment property with immediate cash flow from a known occupant.
Read →What is a dock-to-grade ratio in industrial real estate?
Dock-to-grade ratio in industrial real estate refers to the number of dock-level loading doors relative to the building's floor area, typically expressed as one dock door per X,000 square feet. It is a key specification for distribution and warehousing tenants because it determines how many trucks can load and unload simultaneously and therefore the building's throughput capacity.
Read →What is clear height in a warehouse or distribution centre?
Clear height in a warehouse or distribution centre refers to the usable vertical space from the finished floor to the lowest overhead obstruction — typically the bottom of the roof structure, sprinkler heads, or HVAC equipment. It is the single most important building specification for warehouse tenants because it determines how many racking levels can be installed and therefore how much product can be stored per square foot of floor space.
Read →