Guide to Commercial Property Disposition
By Michael Law · Industrial Real Estate Broker, Lennard Commercial Realty
A commercial property sale can lose momentum long before it reaches the market. An unresolved environmental question, an incomplete lease file, or an asking price that cannot be supported by comparable sales can narrow the buyer pool quickly. This guide to commercial property disposition outlines how industrial owners can prepare, position, negotiate, and close a sale with greater control.
Disposition is more than putting a building on the market. It is the planned exit of a real estate asset, with decisions about timing, buyer targeting, pricing, due diligence, and transaction structure made well before offers arrive. For owners in Toronto and the GTA, where industrial supply, tenant demand, and redevelopment pressure can vary sharply by submarket, that preparation affects both price and certainty of closing.
Guide to Commercial Property Disposition: Start With the Exit
Before selecting a list price or preparing marketing materials, define what a successful disposition means. A seller seeking the highest possible price may accept a longer marketing period, broader due diligence rights, or a more complex buyer profile. A business owner who needs to relocate operations may place greater value on a firm closing date, leaseback flexibility, or limited conditions.
The first questions should be practical. Is the asset vacant, owner-occupied, or tenant-occupied? Does the owner need sale proceeds to fund another acquisition or business expansion? Is there a preferred closing date? Will the sale include excess land, equipment, or a related business operation? These points shape the buyer universe and the transaction structure.
For an owner-occupied industrial property, a sale-leaseback may be worth evaluating. It can release capital while preserving operational continuity, but it also creates a long-term lease obligation and limits future flexibility. For an investment property, the quality and durability of the income stream may matter more to buyers than the building itself. The right disposition strategy depends on the owner’s objective, not simply the strongest recent headline sale.
Establish the ownership and operating picture
A buyer will eventually examine the property through legal, financial, physical, and operational lenses. Sellers should do the same first. Confirm the registered ownership entity, mortgage discharge requirements, easements, access rights, zoning, tax status, and any agreements that could affect a buyer’s use of the site.
For leased properties, review every lease, amendment, renewal option, assignment provision, tenant inducement, security deposit, and arrears record. A lease abstract is useful, but it does not replace the signed documents. Mismatches between a marketing summary and the lease can become a credibility issue during diligence.
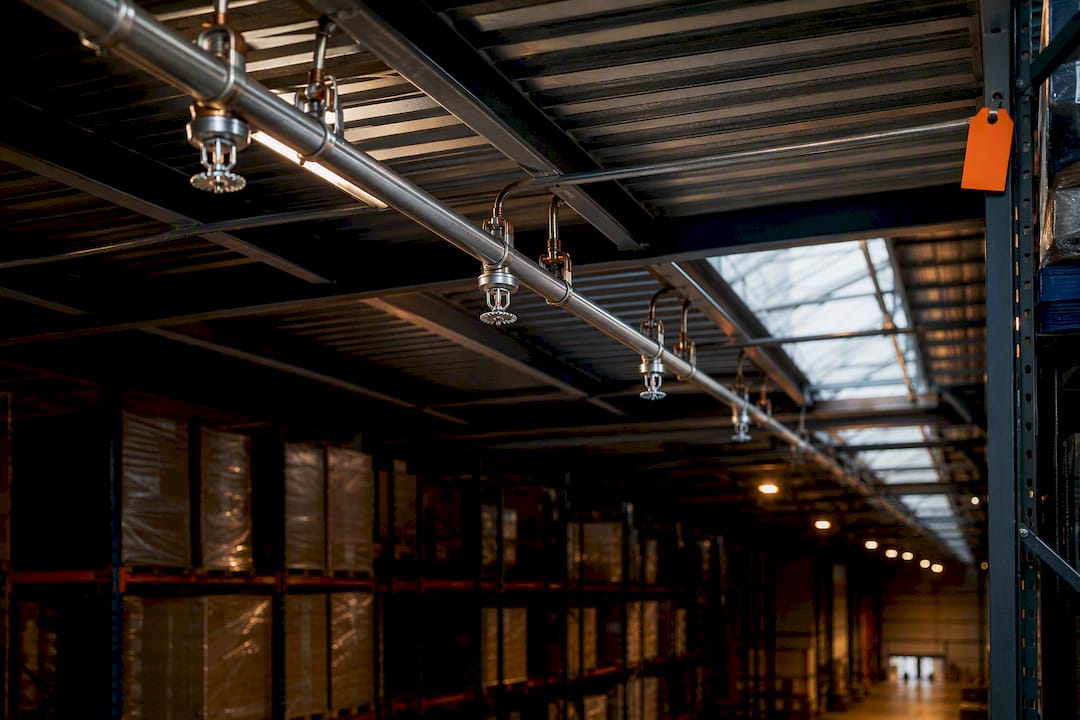
Industrial assets require particular attention to building functionality. Clear height, shipping configuration, trailer parking, power capacity, sprinkler systems, office finish, yard use, environmental history, and truck circulation can all influence value. A buyer assessing manufacturing, logistics, or contractor use may view a practical deficiency differently than an investor focused on rental income.
Build a Defensible Value Range
The most effective pricing process is evidence-based and purpose-specific. Comparable sales are necessary, but they are not enough. A recently sold industrial building may differ in clear height, site coverage, zoning, tenant profile, condition, or ability to accommodate modern distribution requirements. Those differences must be translated into a meaningful value adjustment.
A proper valuation review considers recent sales, active listings, available supply, lease comparables, replacement cost, land value, and the likely buyer pool. It should also account for the property’s current occupancy. A vacant building may attract end users willing to pay for immediate possession, while a leased property may be valued primarily on its net operating income, tenant covenant, and remaining lease term.
Avoid treating the asking price as a negotiation cushion. An aggressive price can be justified when demand is deep and the asset has clear competitive advantages. But a price that exceeds market evidence without a credible explanation can result in extended exposure, repeated buyer objections, and less leverage once the property becomes stale.
A value range is often more useful internally than a single number. It helps the owner decide what terms, conditions, and timing trade-offs are acceptable before negotiations become emotional.
Prepare the Property Before Marketing
The strongest marketing campaign cannot repair preventable uncertainty. Prepare a complete, organized diligence file before outreach begins. This allows qualified buyers to make decisions faster and reduces the risk of a late-stage retrade.
A seller’s package will vary by asset, but it commonly includes:
- legal descriptions, surveys, title materials, and zoning information;
- property tax bills, utility information, and operating expense records;
- leases, rent rolls, tenant correspondence, and payment history where applicable;
- floor plans, site plans, building specifications, and records of capital improvements;
- environmental reports, permits, inspection records, and known remediation information; and
- details on mortgages, contracts, or restrictions that could affect closing.
The purpose is not to overwhelm every prospect with confidential documents. Sensitive material should be released in stages, often after a confidentiality agreement and evidence of financial capacity. The point is to have reliable information ready when a serious buyer needs it.
Physical preparation also matters. Address visible deferred maintenance, clear unnecessary storage, organize mechanical rooms, and ensure loading areas are presentable. These steps do not change the property’s structural fundamentals, but they improve first impressions and signal that the asset has been responsibly managed.
Choose the Right Marketing Process
Commercial property disposition does not always require the widest possible exposure. A broad campaign can create competition and reach buyers who are not already active in the local market. It may be appropriate for a vacant industrial building, a well-located investment asset, or a property with flexible use potential.
A controlled process can be better when confidentiality is critical. Owners operating a business from the property may not want employees, customers, competitors, or suppliers learning about a pending sale. In those cases, targeted outreach to prequalified buyers can protect operations while still producing competitive interest.
The trade-off is straightforward: a quieter process provides discretion but may limit market tension; a broad process increases visibility but requires more coordination and information control. The right approach should reflect the asset, the owner’s timeline, and the consequences of disclosure.
Marketing materials should present the facts clearly. They should explain the property’s location, building specifications, current income or vacancy status, permitted uses, redevelopment or expansion potential where supportable, and key transaction parameters. Unsupported claims create problems later. Specific, verifiable information builds confidence.
Evaluate Offers Beyond the Purchase Price
The highest offer is not always the best offer. A strong purchase price can be offset by broad due diligence conditions, uncertain financing, a long conditional period, extensive representations, or a buyer with limited experience completing comparable transactions.
Compare offers as complete business proposals. Consider deposit amount and timing, proof of funds, financing conditions, inspection rights, environmental conditions, requested seller warranties, closing date, and remedies if either party fails to close. If several offers are expected, establish a disciplined process for reviewing them and communicating deadlines.
A buyer asking for an extensive diligence period may be entirely reasonable for a complex property. The issue is whether the scope, timing, and termination rights are proportionate to the information already available. The more uncertainty a seller eliminates before the offer stage, the easier it is to negotiate focused conditions rather than open-ended ones.
Negotiation should protect both economics and execution. For example, accepting a slightly lower price from a well-capitalized buyer with a meaningful deposit and a short, defined diligence period may be preferable to pursuing a higher but uncertain proposal. Sellers should be clear on their priorities before the first counteroffer is drafted.
Manage Diligence and Closing With Discipline
Once an agreement is signed, the transaction enters its most demanding phase. Buyers will test the assumptions behind their offer through legal review, inspections, financing, appraisal, environmental assessment, lease review, and operational verification. A delayed answer or missing document can create unnecessary concern.
Assign responsibility for each diligence request and maintain a single current record of documents provided, questions raised, deadlines, and outstanding items. Do not make informal assurances that conflict with the purchase agreement or existing records. When an issue arises, address it directly with the appropriate advisors and explain the proposed path forward.
Closing preparation should begin well before the closing date. Confirm mortgage payout figures, discharge requirements, tenant notices, utility transfers, insurance arrangements, keys, access devices, and any post-closing obligations. If the sale involves a leaseback, occupancy agreement, or transitional use of the premises, document the operational details carefully. Ambiguity over possession, repairs, insurance, or access can create problems after funds have changed hands.
Commercial real estate counsel and tax advisors should be engaged early enough to identify structure issues before they become closing obstacles. A property sale can have consequences beyond the purchase price, including tax treatment, corporate planning, and liability allocation. Those questions should be addressed based on the owner’s circumstances, not handled as an afterthought.
A well-run disposition gives the seller options. Preparation creates leverage, accurate pricing attracts credible interest, and disciplined diligence protects the deal when scrutiny increases. Before taking an industrial asset to market, take the time to identify what could concern a buyer and resolve, explain, or price that issue with intention.
About Michael Law
Managing Partner and Industrial Real Estate Broker at Lennard Commercial Realty. Representing tenants and landlords across Toronto and the GTA for 15+ years. Michael specializes in GTA industrial real estate — connect with Toronto's leading industrial broker at mlawrealestate.com/industrial-broker-toronto.