
Industrial Investment in the GTA: What the Numbers Say
By Michael Law · Industrial Real Estate Broker, Lennard Commercial Realty
Industrial investment in the GTA is a market of two speeds in late 2026: modern, well-located buildings still price firmly, while older and speculative product is repricing. Investors who do well here underwrite building by building and submarket by submarket, not the region as a whole. That is the work we do as industrial brokers: Michael Law of Lennard Commercial advises owners, investors and tenants across the Greater Toronto Area, and the figures below are the ones we would put in front of a client before any offer.
TL;DR
- GTA industrial transaction volume rose 10% year over year to $4.4 billion through Q3 2026, so capital is still active even with trade uncertainty.
- Availability is up (5.3% in Toronto per one data set) while a different brokerage survey shows vacancy near 2.6%. The two measure different things, so know which one you are reading.
- Asking net rents sit near $16 per sq ft, about 38% above five years ago but down from the peak. Older 18 to 22 ft clear buildings carry the most repricing risk.
- New supply is the main risk: 43 projects totalling 12.3 million sq ft are under construction, and nearly two-thirds of that space is uncommitted.
- Submarket, clear height and lease term matter more than the regional average.
Table of Contents
- How big is the GTA industrial market, and why do investors hold it?
- What deal activity looks like in 2026
- Vacancy, availability and rents: reading the numbers correctly
- The supply pipeline is the biggest variable
- Submarkets and building specs: where returns diverge
- Which property types are drawing capital
- Risks to price before you buy
- What this means for owners and occupiers
- Our view: buy the building, not the headline
- Working with an industrial broker on a GTA acquisition or sale
- FAQ
- Sources
How big is the GTA industrial market, and why do investors hold it?
The GTA is the fourth-largest industrial market in North America, according to CPECN’s January 2026 coverage. Industrial investment here means owning or buying warehouses, distribution centres, manufacturing buildings, cold storage, truck terminals and outside-storage yards, either to occupy (a user purchase) or to lease to tenants (an investment purchase).
The reasons capital keeps coming back have not changed. A RENX contributor in May 2026 pointed to three fundamentals: very tight development land supply, a deep labour market, and proximity to more than 15 million consumers. The same piece is clear that effortless rent growth is over. What the market now rewards is knowing which submarkets are tightening and which building vintages are losing the functionality battle.
For an investor, that shifts the question from “is GTA industrial a good market?” to “which asset, bought at what basis, with what lease roll?”
What deal activity looks like in 2026
Altus Group reports that GTA industrial transaction volume rose 10% year over year to $4.4 billion through the third quarter of 2026. The same report notes that some major logistics occupiers continue to favour just-in-case inventory strategies in response to tariff risk and transportation constraints, which supports demand for well-located distribution space.
Two points follow for a buyer:
- Industrial is holding up in a year when total GTA commercial investment volume rose 39% to $15.1 billion, driven mostly by office and multi-family. Industrial is not the fastest-growing category this year, but it is liquid.
- Pricing is converging. RENX’s May 2026 coverage describes cap rates having adjusted so that the spread between asking and transacting prices on quality GTA industrial assets is narrowing. In plain terms, sellers and buyers are closer on value than they were a year or two ago, which makes well-prepared offers on good buildings more likely to close.
A cap rate is the net operating income of a property divided by its price. It is the quickest way to compare what you earn on one building against another. We cover how to read it in more detail in our guide to industrial cap rates for GTA investments.
Vacancy, availability and rents: reading the numbers correctly
Investors often quote GTA “vacancy” without noting that sources use different definitions. Here are the Q3 2026 readings side by side.
| Measure | Reading | Source and period |
|---|---|---|
| Toronto availability rate | 5.3%, up 60 bps year over year | Altus Group, Q3 2026 |
| GTA vacancy rate | 2.6%, down from 3.2% a year earlier | Brokerage survey via Canadian Mortgage Professional, Q3 2026 |
| Average asking net rent | $16.06 per sq ft, down 4.8% year over year | Same survey, Q3 2026 |
| Rent versus five years ago | About 38% higher | Same survey, Q3 2026 |
| Net absorption | 2.2 million sq ft in the quarter, 11.2 million sq ft year to date | Same survey, Q3 2026 |
Availability counts all space marketed for lease, including space that is still occupied by a tenant who has given notice or is subleasing. Vacancy counts only space that is physically empty. Availability therefore runs higher and is the better early signal of how much choice tenants have. Both are published quarterly and revised, so check the latest release before you underwrite.
What this means in practice: tenants have more options than the low vacancy figure suggests, and landlords of legacy buildings are feeling it first. Altus notes that tenants are using the wider range of available space to secure concessions and tenant improvement allowances in older properties, while pricing and terms on build-to-suit and high-specification Class A buildings remain firm.
For a deeper look at why the metric matters to returns, see our note on GTA industrial vacancy rates for investors.
The supply pipeline is the biggest variable
The Altus Canadian industrial update for Q3 2026 shows the GTA remains Canada’s primary development centre, with 43 projects totalling 12.3 million sq ft under construction and nearly 63% still available. Nine projects delivered close to 2.5 million sq ft in the quarter, and 85% of that was uncommitted at quarter-end.

Connect CRE Canada reports that net absorption turned negative in the quarter after four consecutive quarters of gains, while asking rents have held in a $16 to $17 per sq ft band since early 2025. Altus senior research analyst Jennifer Nhieu attributes the pressure to speculative projects delivered without pre-leasing, and notes that tariffs, trade uncertainty and cost control are slowing tenant decisions, with some businesses consolidating rather than expanding.
There is a counterweight. Rents needed to justify new construction remain well above current market rents, which keeps development muted into 2026 and 2027 according to a national brokerage executive quoted by Yahoo Finance Canada. The same coverage observed that incentives such as free rent were already contracting in core markets after a strong Q4 2025 absorption rebound, a pattern that often comes before firmer pricing.
So the pipeline cuts two ways. Buildings already delivered and unleased will compete for tenants through 2027. But few new projects are being started, which limits future competition for the buildings you buy today.
If you are assessing a newly delivered or under-construction building, treat the physical shell as part of the risk review. Roof condition, membranes and drainage drive capital costs on large flat-roof buildings, and a specialist view on industrial roofing in the GTA can inform the reserve you carry in your model.
Submarkets and building specs: where returns diverge
The regional average hides sharp differences. The Q3 2026 survey reported via Canadian Mortgage Professional shows:
- GTA North: the lowest vacancy at 2.0% and the highest average asking net rent at $17.63 per sq ft.
- GTA East: still elevated at 5.0% vacancy.
- GTA West: the most improved, with vacancy down 30 bps to 2.6%.
- Clear height: buildings with 30 ft or more clear commanded $16.84 per sq ft against $14.86 for 18 to 21 ft clear.
That $2 per sq ft spread is the market telling you what tenants value: ceiling height for racking density, more dock doors, wide truck courts and modern power. Older 1980s and 1990s product with 18 to 22 ft clear heights now rents at roughly $15 to $16 net per sq ft, according to RENX’s May 2026 article, against peak levels above $22. Lennard Commercial’s own analysis was part of that coverage.
In practice, a buyer of older product should underwrite the following:
- The in-place rent versus today’s market rent at lease expiry.
- The cost to re-tenant: downtime, tenant improvement allowance and leasing commissions.
- Whether the site has an alternative value, such as extra land for outside storage, trucking use or redevelopment.
A buyer of modern product is paying for durability of demand, and needs to confirm the tenant covenant and the length of the term.
We track where demand is concentrating in our review of top GTA industrial submarkets, and our GTA industrial market page keeps the quarterly picture in one place.

Which property types are drawing capital
Altus expects Canada’s industrial market to settle into a post-expansion equilibrium in which asset quality, location and an occupier’s exposure to trade and demographic shifts decide performance. Near-term demand is strongest for modern logistics, build-to-suit, cold storage and manufacturing facilities in supply-constrained or high-population-growth markets. Legacy properties and uncommitted speculative buildings face longer lease-up, more concessions and higher repricing risk.
CPECN’s January 2026 report adds that experts see long-term fundamentals as strong despite cautious sentiment, with population growth and evolving supply chains continuing to support logistics demand.
For an investor, this suggests a rough ranking of how much conviction each type deserves:
| Property type | What supports it | What to underwrite |
|---|---|---|
| Modern logistics and distribution | Absorption led by logistics and distribution users in Q3 2026 | Tenant covenant, lease term, rent versus market |
| Cold storage and food-grade | Altus lists cold storage among the strongest near-term demand categories | Refrigeration systems, power, floor and dock specs |
| Manufacturing and high-power | Demand in supply-constrained markets | Power capacity, zoning, special-use permissions |
| Older bulk warehouse | Lower entry price | Re-leasing cost, clear height, rent reset at expiry |
| Outside storage and truck terminals | Scarce land in the GTA | Zoning, site coverage, access |
We place tenants and buyers in all of these categories, including the specialized ones listed on our services page, from cold storage to hazardous-material and data-centre sites.
Risks to price before you buy
Every risk below shows up in the data above, so each can be priced instead of feared.
Lease-up risk. With 85% of Q3 deliveries uncommitted, a vacant or partially leased building should be priced on a realistic absorption period, not on a pro forma that assumes immediate occupancy.
Rent reset risk. Rents are about 4.8% lower year over year, per the survey figure above. A lease signed at peak may roll down. Model the expiry, not just the in-place rent.
Interest rate and trade risk. Altus links the rise in availability to a wave of deliveries meeting a selective tenant base, with elevated interest rates and cross-border trade friction making tenants cautious. Test your returns at more than one financing cost.
Operational risk. Maintenance backlogs in older buildings affect net income. If you own and operate, systems that track equipment, preventive maintenance and work orders, such as asset tracking for industrial operations, help you keep the building in the condition the next tenant expects.
Tenant concentration. Some occupiers are consolidating rather than expanding. A single-tenant building with a consolidating tenant needs a renewal view well before expiry. Our guide to industrial property tenants for GTA owners shows how different tenant types behave.
What this means for owners and occupiers
Investors are not the only ones affected. If you own and lease space, tenant inducements are higher on older buildings, so pricing a renewal early matters. If you occupy space, you have more choice than at any time in recent years, and the market currently favours organized, well-informed tenants.
For occupiers weighing expansion, consolidation or relocation, the practical points are these:
- Compare availability, not just vacancy, in your submarket.
- Ask for concessions and tenant improvement allowances on legacy buildings, where Altus says tenants are securing them.
- Do not assume Class A terms will soften: they have remained firm.
- Consider a user purchase if you have a long horizon and the numbers beat your lease cost.
The broader resilience case is covered in our piece on why GTA industrial property holds up, and our 2026 trends review shows how the year developed.
Our view: buy the building, not the headline
Looking across fifteen-plus years in Ontario industrial, the pattern we see in this market is a split between buildings that tenants compete for and buildings they negotiate against. Regional averages blur that split, and a sound acquisition lives on the right side of it.
Our approach is to start from the submarket and the specification: clear height, dock count, power, truck court, site coverage. Then we test the lease. A short lease on a modern building in a tightening submarket is a different bet from a long lease on a 1980s building that will roll to a lower market rent. Both can make sense at the right price, and neither makes sense at the wrong one.
We also think the market is giving a window to well-advised buyers. Tenant inducements are higher, pricing between buyers and sellers is converging, and new development is muted into 2026 and 2027 because current rents do not justify building. That combination rewards patience and good data more than speed.
Our work covers both sides of the table, tenant representation, landlord representation, investment sales and user purchases, which gives us a direct view of what tenants will pay and what buyers will accept. We bring over $2.5B in closed Ontario industrial transactions and real-time data to each mandate.
Michael Law
Working with an industrial broker on a GTA acquisition or sale
We represent investors, owners and occupiers on investment sales, user sales and purchases, lease renewals and relocations, and landlord assignments across the GTA, with specialist coverage for cold storage, manufacturing, truck terminals, e-commerce fulfillment and other specialized space. Our GTA industrial broker page explains how an engagement runs, and you can see the full range on our services page.
If you are weighing a purchase, a sale or a repositioning, contact Michael Law at Lennard Commercial with the address or the submarket and the size range, and we will tell you where the building sits against current market data.
FAQ
Is the GTA a good market for industrial investment in 2026?
The fundamentals remain supportive: tight land supply, a deep labour pool and access to more than 15 million consumers. Deal volume reached $4.4 billion through Q3 2026, up 10% year over year. Returns depend heavily on the asset, because modern buildings hold pricing while older ones face concessions and rent resets.
Why do vacancy and availability figures differ?
Vacancy counts only physically empty space. Availability also counts space that is on the market but still occupied, for example by a tenant on notice or a sublease. Different firms also survey different building sets, so a 2.6% vacancy reading and a 5.3% availability reading can both be correct for the same quarter.
What are GTA industrial rents now?
The Q3 2026 survey reported average asking net rents of $16.06 per sq ft, down 4.8% year over year but about 38% above five years earlier. Rents differ by submarket and spec, from $14.86 for 18 to 21 ft clear buildings to $17.63 in GTA North. These figures update quarterly, so check the latest release.
Should I buy or lease industrial space in the GTA?
It depends on your horizon, capital and how specialized the building must be. A user purchase can make sense for a business with stable, long-term space needs, while leasing keeps capital free and is attractive when tenants have leverage. We model both against your cost of capital before recommending one.
Sources
- Built To Last: Industrial Real Estate In The GTA (CPECN)
- Toronto commercial market update, Q3 2026 (Altus Group)
- Canadian industrial market update, Q3 2026 (Altus Group)
- 85% Of New GTA Industrial Space Remains Unleased (Connect CRE)
- GTA industrial rents fall in Q3 (Canadian Mortgage Professional)
- GTA industrial real estate: The floor is in but recovery will be uneven (RENX)
- Canada’s industrial real estate markets on different paths (Yahoo Finance Canada)
Recommended
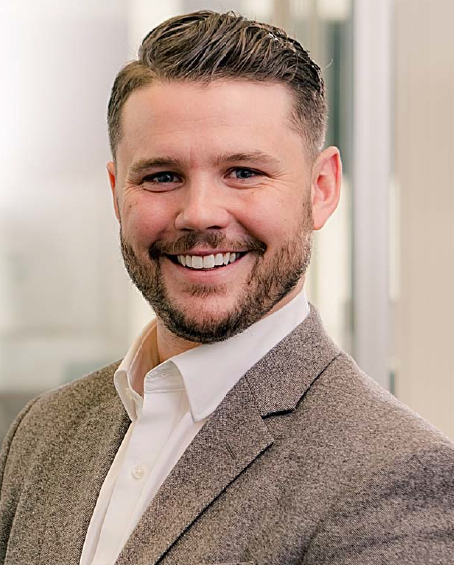
About Michael Law
Managing Partner and Industrial Real Estate Broker at Lennard Commercial Realty. Representing tenants and landlords across Toronto and the GTA for 15+ years. Michael specializes in GTA industrial real estate — connect with Toronto's leading industrial broker at mlawrealestate.com/industrial-broker-toronto.
Related Articles


More Toronto Industrial Real Estate Insights
Articles & Analysis
Industrial Construction Costs in Ontario: 2026 Guide
What it costs to build a warehouse, plant or cold storage facility in the GTA in 2026: per-square-foot ranges, soft costs, price indexes and the build-or-lease test.
Read →Warehouse Sublease Versus Assignment Explained
Read →Commercial Appraisal Firms in Toronto: How to Choose
How to choose a commercial appraisal firm in Toronto for an industrial property: services, AACI credentials, fees, timelines and what to prepare.
Read →Manufacturing Space Power Requirements in the GTA
What electrical service a manufacturing space needs in Ontario: load calculations, voltage, the 80% rule, utility lead times and how to check capacity before you lease.
Read →Dock Door Ratios: How Many Doors Does an Industrial Building Need?
Dock door ratios explained for GTA industrial tenants: typical square feet per door, how to calculate your own number, and what to check before you sign a lease.
Read →Common Questions
What is the difference between a base building and turnkey industrial lease?
In a base building industrial lease, the landlord delivers the premises in a shell or base condition and the tenant is responsible for completing improvements to make the space operational — often funded through a tenant improvement (TI) allowance from the landlord. In a turnkey lease, the landlord constructs or fits out the space to the tenant's specifications and delivers it ready to occupy, typically at a higher base rent.
Read →What is CAM (common area maintenance) in industrial real estate?
CAM, or common area maintenance, refers to the costs a tenant pays — on top of base rent — for the upkeep and operation of shared areas in a multi-tenant industrial building. In a typical GTA industrial net lease, CAM is one component of the operating cost recovery alongside property taxes and building insurance, and is charged on a per-square-foot basis proportional to the tenant's share of the building.
Read →What is a right of first refusal in an industrial lease?
A right of first refusal (ROFR) in an industrial lease gives the tenant the contractual right to match any third-party offer the landlord receives on an adjacent or specified space before the landlord can lease it to someone else. It is a space-control tool that lets an expanding tenant secure future growth space without committing to it upfront.
Read →